ÖğrenmeBilim ve teknoloji18 yaş ve üzeriKapalı alan
Finance and Stochastics Seminar – Mao Fabrice Djete
17 Kasım 2026 Salı · 14:00140, Huxley Building, South Kensington CampusÜcretsiz
imperialCollege sayfasında açMao Fabrice Djete'nin sunduğu, ölçüye bağlı kontrol problemleri için BSDE'ler üzerine ücretsiz akademik seminer.
Hakkında
İngilizceye çevriliyor…
Speaker: Mao Fabrice Djete Title: A New Notion of BSDE for Measure-Dependent Control Problems and Its Applications Abstract: I will introduce a notion of backward stochastic differential equation (BSDE) for optimization problems with measure dependence. I will begin with two examples that illustrate why a new formulation is needed: a “robust” principal–agent problem and a mean-field optimal stopping problem. I will then develop the BSDE formulation in the Markovian setting before turning to the non-Markovian case. Finally, I will discuss what well-posedness of these equations tells us about t…
Bunlar da hoşuna gidebilir
16 Kas Pzt · 13:00
Biyomatematik Semineri – Emilie Devijver (Université Grenoble Alpes)
140, Huxley Building, South Kensington Campus
14 Kas Cmt
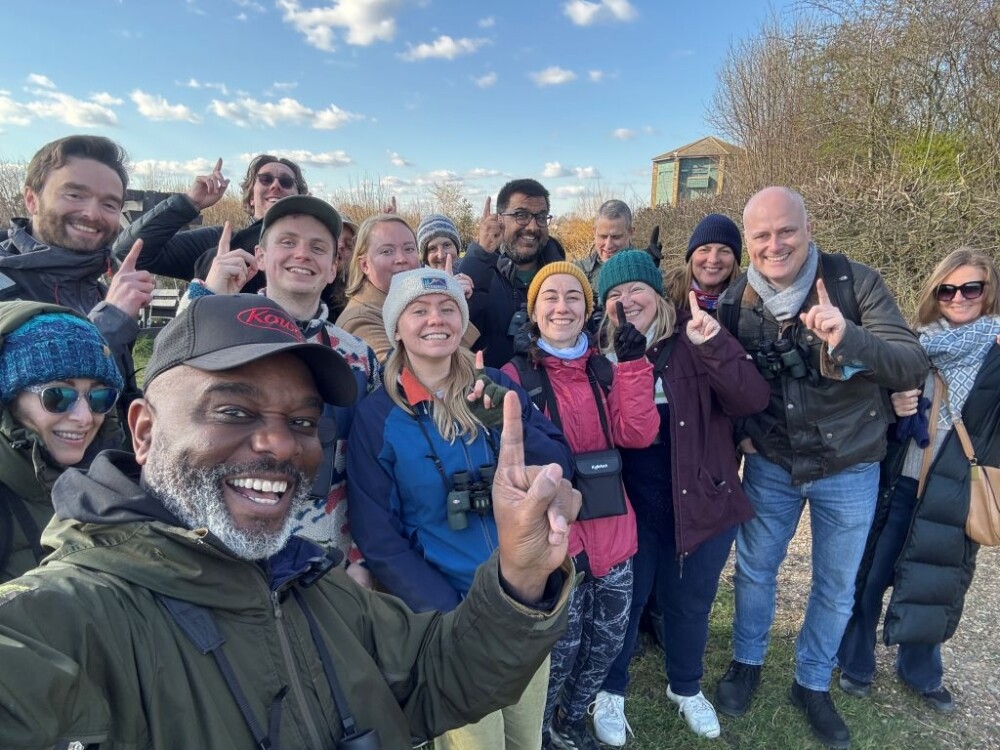
Urban Birder Kursu - Kasım
WWT London Wetland Centre

14 Kas Cmt · 09:00
Lycée Français Charles de Gaulle Açık Kapı Günü 2026 - 14 Kasım
Lycée Français Charles de Gaulle

14 Kas Cmt · 09:15
GLP-1'lerin Işık ve Gölge Yüzü
Basinghall
14 Kas Cmt · 09:30
Yazı Grubu
Brixton Oval, London, SW2 1JQ

14 Kas Cmt · 09:30
Mikrobiyom-İltihap Ekseni: Mekanizmaları Sonuçlara Dönüştürmek
The Minster Building
Londra için benzer etkinlikler

14 Kas Cmt · 10:00
Independent Schools Show, Autumn 2026
The Royal Horticultural Halls, Lindley Hall and Lawrence Hall

15 Kas Paz
LGBTQ+ tarih söyleşileri
National Maritime Museum
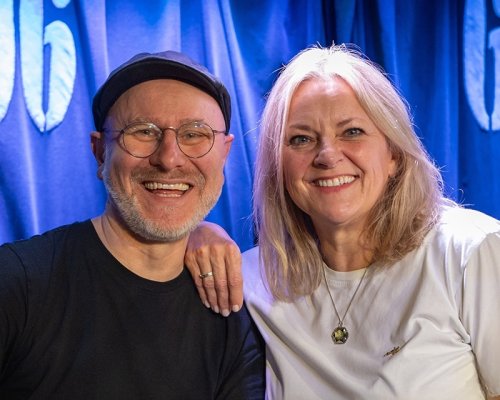
14 Kas Cmt · 10:00
Claire Martin/Stefan Holmstrom – Caz Şarkıcısı Atölyesi
606 Club

15 Kas Paz
Roma kale kapısı turları
London Museum Docklands

14 Kas Cmt · 09:45
British Museum’da Arkeoloji Hızlandırılmış Kursu
The British Museum

14 Kas Cmt
Skate School & Kids Skate Club
Somerset House
Haftalık e-posta